
Bitdefender Box 2 (Recommended)
Bitdefender BOX 2 is a powerful Wi-Fi security tool that will protect all your IoT devices against malware attacks.This cybersecurity hub builds up...
Search results for fiber, optical network, data center, telecom power and outdoor communications infrastructure topics.
The combined entity, VodafoneThree, marks the biggest shake-up in the British telecoms sector in years. 1 In many regions and countries, wireless telecom markets are fragmented, and some players are subscale. Historically, regulators have focused on maximizing competition by. This article, the final in our three-part series on M&A technology carveouts, delves into the complexities of telecom mergers, focusing on the critical elements needed to achieve a seamless integration. Drawing on lessons from past telecom integrations and broader M&A experiences, I explore the. This analysis highlights the intricate landscape of 4-to-3 mobile mergers, where economic theories, technical synergies, and real-world cases reveal the multi-faceted implications for consumers, companies, and regulators alike. As telecommunications infrastructure becomes more complex and data. Large telecom mergers are built on bold promises: broader coverage, faster rollouts, lower costs, and better service. With scale, spectrum, and capital aligned, the opportunity is real.
[PDF Version]
Ethernet RJ45 patch panel is an ideal method to create a flexible, reliable and tidy cabling system no matter for home network or data centers. Today, various styles of copper patch panels can be found in the market, such as shielded or unshielded patch panel, flat or angled patch panel, etc. They come in a range of sizes, and are typically mountable, whether that's on a wall, or on a rack to make for easier. FastLinkcabsys RJ45 1U patch panel is a crucial component for any structure cabling solution. Whether in office settings or high-density data centers, our patch. Patch Panels RJ45 Modular Connectors / Ethernet Connectors are available at Mouser Electronics.
Dubai Data Centers | Premium Colocation Provider and Equinix Dubai is your strategic interconnection hub in the MENA region, and the first carrier-neutral.
[PDF Version]
How to Connect a Splitter to Another Splitter: A Complete. In this guide, we'll explain how to safely connect a splitter to another splitter, covering b.
[PDF Version]
Telecom Products Manufacturer, Contractor PhilippinesManufacturers, importers, local distributors, suppliers of TELECOM products and brands. Vendors, contr.
[PDF Version]
Complete Guide to Patch Panels: Types, Benefits, and Discover everything you need to know about patch panels, including different types, their benefits, an.
[PDF Version]
Papua New Guinea's fishery installs Zella Pro Edge data center“We've introduced Zellabox to one of our sites, a micro data center designed for versatile en.
[PDF Version]
Best home network firewall devices in 2026 [We tested 5]Our expert team of testers, using their 15+ years combined experience, have tested the best devices.
[PDF Version]Bitdefender BOX 2 is a powerful Wi-Fi security tool that will protect all your IoT devices against malware attacks.This cybersecurity hub builds up...
Another firewall device that can protect your home network is Ubiquiti Unifi Security Gateway. This device has three 1Gpbs Ethernet ports, and it u...
Protecting your home or business network is important, and you can do that easily with this device. This firewall comes with intrusion prevention,...
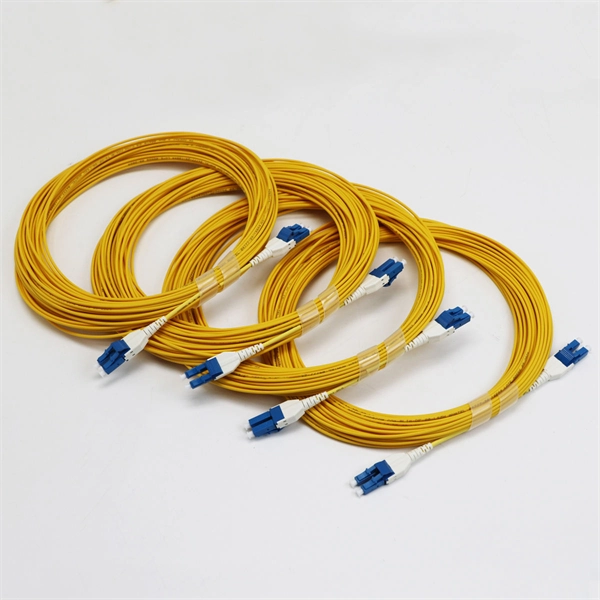
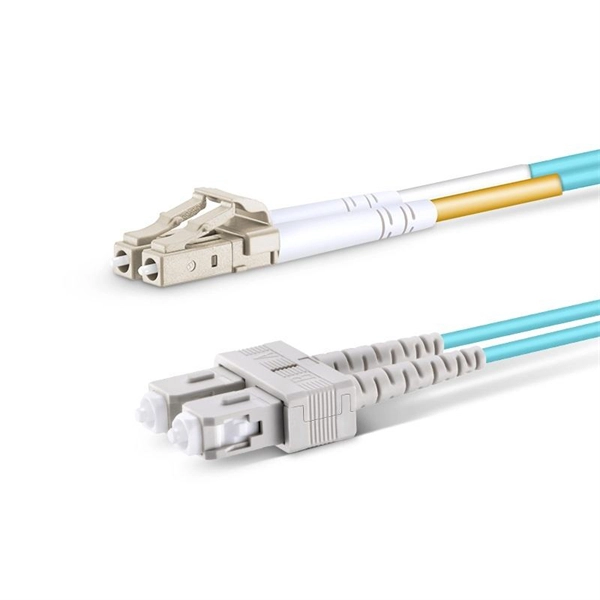
Fiber Connector Types: A Comprehensive Guide 2025Among these components, fiber connector types are essential to network performance, reliability, and scala.
[PDF Version]Use the inquiry form to describe the product category, application, interfaces, capacity and installation environment.